
Understand the Number. Then Make the Decision.
Simple calculations. Better questions. More conscious financial decisions.
There is no shortage of websites, spreadsheets, apps and AI tools that can calculate almost anything about your money.
Loan EMIs.
Compound interest.
Rental yield.
Net worth.
Investment returns.
Prepayment savings.
You can get the mathematical answer in seconds.
But a calculation is not a decision.
And that is why I created Money Lab.
I don’t want to build another complicated financial calculator.
I want to help you understand the basic number behind a financial decision, so that you can pause, question it and make a more informed call.
Because sometimes the most important financial question isn’t:
“What is the answer?”
It is:
“What does this answer mean for me?”
Why Money Lab?
Over 30+ years across banking, NBFCs, insurance, fintech, lending and asset finance, I have seen how easily people can become dependent on numbers they don’t fully understand.
A financial product may come with:
A return.
An interest rate.
A tenure.
A yield.
A tax benefit.
A fee.
But the number alone doesn’t tell you whether the decision is right for your circumstances.
That’s where
Money Lab
comes in.
The calculation is the starting point. Not the conclusion.
I want you to understand enough to ask better questions.
The Money Lab Rule
Don’t blindly trust the calculator. Understand what it is telling you.
Every tool here follows three simple steps:
- Calculate
Get the basic number.
- Understand
Know what that number means in practical terms.
- Decide Consciously
Consider your circumstances, alternatives, risks and priorities before taking the call.
That’s it.
No complicated formulas for the sake of complexity.
No financial jargon designed to impress you.
No black box
1.SALARY DEPENDENCY
How long could your lifestyle survive without your salary?
Your salary may be ₹20 lakh, ₹40 lakh or ₹1 crore a year.
But salary is an income stream, not necessarily wealth.
A simple starting calculation is:
Financial Runway = Available Liquid Savings ÷ Monthly Essential Expenses
For example:
If you have:
₹12 lakh available savings
and your essential monthly expenses are:
₹1 lakh
your basic financial runway is approximately:
12 months
That doesn’t mean you are financially independent.
It simply tells you how long your current liquid resources could potentially support your essential lifestyle if your salary stopped.
The bigger question
What would happen after those 12 months?
And how much of your lifestyle is dependent on continuing to earn?
→ Check Your Salary Dependency

2.NET WORTH
What do you actually own after subtracting what you owe?
Net worth sounds complicated.
The basic calculation isn’t:
Net Worth = Total Assets − Total Liabilities
If you own:
- Home: ₹1.50 crore
- Investments: ₹30 lakh
- Bank deposits: ₹10 lakh
- Other assets: ₹10 lakh
Your total assets are:
₹2 crore
If your outstanding loans and other liabilities total:
₹70 lakh
your approximate net worth is:
₹1.30 crore
Simple.
But here’s where the interesting conversation begins.
Is all ₹1.30 crore equally useful to you?
Probably not.
Some may be locked into property.
Some may be liquid.
Some may generate income.
Some may simply appreciate in value.
So I don’t want Money Lab to stop at:
“Your net worth is ₹1.30 crore.”
I want you to ask:
“What is my wealth actually doing for me?”
→ Calculate Your Net Worth
3. RENTAL YIELD
Your property may be worth ₹1 crore. But what is it actually earning?
A simple starting calculation is:
Gross Rental Yield = Annual Rent ÷ Current Property Value × 100
Suppose a property is worth:
₹1 crore
and generates:
₹30,000 per month
Annual rent:
₹3.60 lakh
Gross rental yield:
₹3.60 lakh ÷ ₹1 crore × 100 = 3.6%
That’s the basic number.
But don’t stop there.
Vacancy.
Maintenance.
Repairs.
Property tax.
Management costs.
Financing costs.
All can affect the actual economics.
The real question is not simply “What is my rental yield?”
It is:
“Is this asset producing enough income for the capital, risk and effort involved?”
That is a much more useful question.
→ Calculate Your Rental Yield
3.LOAN PREPAYMENT
What happens if you put ₹5 lakh into your outstanding loan?
The basic principle is simple.
The potential interest saving depends on:
Outstanding loan
Interest rate
Remaining tenure
Amount being prepaid
A ₹5 lakh prepayment on a loan carrying 9% interest does not simply mean :
“I saved ₹45,000.”
Because the actual saving depends on the outstanding balance, remaining tenure, EMI structure and how the lender recalculates the loan.
That is why the calculator gives you an estimate based on the inputs you provide.
But the bigger question is:
Should you prepay at all?
You may have other uses for that ₹5 lakh.
You may need liquidity.
You may have higher-cost debt.
You may have an investment opportunity.
You may simply value becoming debt-free sooner.
The calculator can show you the financial impact.
Only you can decide the value of the alternatives.
→ Understand Your Loan Prepayment Impact

4. RENT VS BUY
Don’t ask me which is better. Ask when each makes sense.
This is one of the most emotionally charged financial decisions.
The basic comparison starts with:
Rent you would pay
versus
EMI + down payment + ownership costs
But that isn’t the whole story.
You also need to think about:
Property appreciation.
Investment return on the down payment.
Loan interest.
Maintenance.
Transaction costs.
Length of stay.
Liquidity.
Flexibility.
And your own life plans.
So Money Lab will not give you a simplistic:
“BUY” or “RENT”
answer.
It will help you understand the assumptions behind the comparison.
Because the right decision for a 25-year-old professional may be completely different from the right decision for a 50-year-old business owner
5. ASSET PRODUCTIVITY
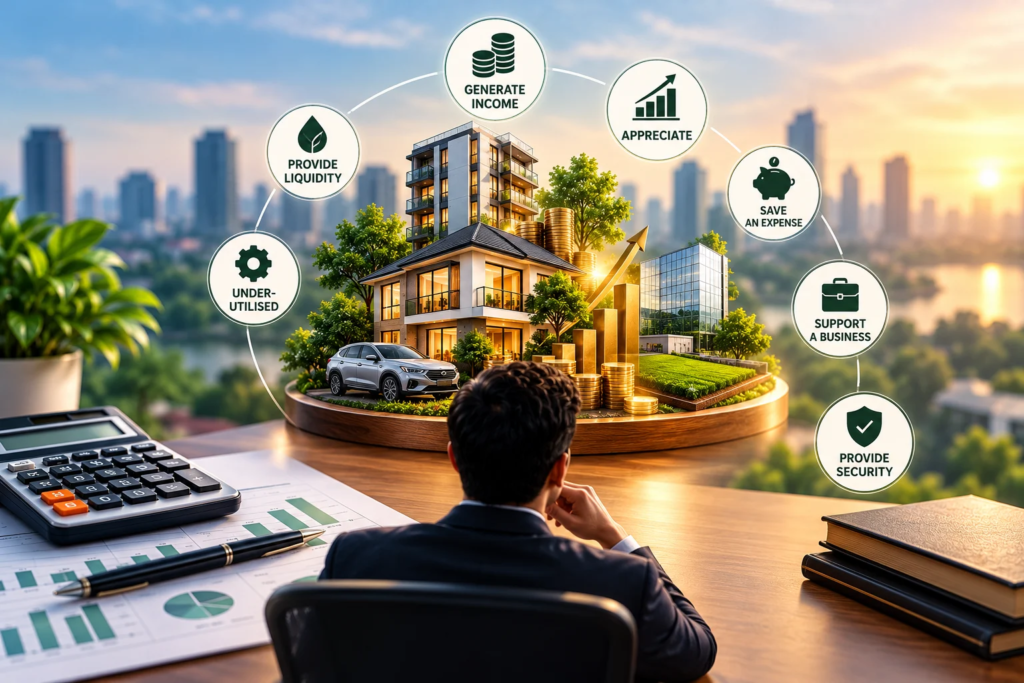
You own the asset. But what is the asset doing for you?
This is one of the questions closest to my own philosophy.
An asset may:
Generate income.
Appreciate.
Save an expense.
Support a business.
Provide security.
Provide liquidity.
Or it may simply remain under-utilised
A simple starting point for an income-producing asset is:
Asset Income Yield = Annual Income Generated ÷ Current Asset Value × 100
But yield is only one part of the story.
You also need to consider:
Capital appreciation
Risk
Liquidity
Maintenance
Tax
Debt
Effort
Opportunity cost
That is why I prefer the question:
“What is my asset contributing to my financial life?”
rather than simply:
“What is my asset worth?”

6. LIFESTYLE INFLATION
You got the raise. So where did the money go?
Suppose your annual salary increased from:
₹20 lakh → ₹25 lakh
That’s a:
₹5 lakh increase
But if your annual spending increased from:
₹12 lakh → ₹15 lakh
₹3 lakh of the increase has already been absorbed by higher spending.
The remaining:
₹2 lakh
is available for additional saving, investing, debt reduction or other priorities.
The calculation is simple.
The behaviour behind it is not.
Because lifestyle inflation rarely arrives as one big decision.
It arrives through many small ones.
A better car.
A larger house.
More holidays.
More subscriptions.
More convenience.
More EMIs.
The question isn’t whether you should enjoy your money.
You absolutely should.
The question is:
“How much of every additional rupee am I converting into a richer life—and how much am I simply converting into a more expensive lifestyle?”
Why I Keep Money Lab Simple
You will notice something deliberate about these tools.
I am not trying to teach you the mathematics behind financial engineering.
There are already countless websites, financial calculators, spreadsheets and AI tools that can take you deep into formulas, assumptions and technical calculations.
That’s not the purpose of Income Beyond Salary.
My purpose is different.
I want the common person to understand the decision.
If you need a complex calculation, use the specialist tool.
If you need tax advice, speak to a tax professional.
If you need regulated investment advice, seek appropriately qualified and authorised advice.
But before you do any of that:
Understand the basic question first.
Because when you understand the basic economics, you can ask a better question.
And a better question often leads to a better decision.
Money Lab Is Not Here To Tell You What To Do
I don’t want you to leave this page thinking:
“Joydeep told me to buy this.”
or:
“Joydeep told me to take that loan.”
That’s not the purpose.
The purpose is to help you say:
“Now I understand what I need to think about.”
That is a very different proposition.
Financial awareness before financial products.
The Three Questions I Want You To Ask
Before taking an important financial decision, ask:
WHAT DOES THE NUMBER SAY?
Understand the basic economics.
WHAT DOES THE NUMBER NOT SAY?
Consider risk, liquidity, tax, effort, opportunity cost and your personal circumstances.
WHAT MATTERS TO ME?
Because the mathematically optimal decision may not always be the decision that best fits your life.
And This Is Where Money Lab Meets Income Beyond Salary
I don’t believe becoming wealthy is simply about earning more.
It is about learning to make better use of:
What you earn.
What you own.
What you borrow.
What you invest.
What you build.
And eventually:
What you choose to do with the wealth you create.
The calculation is only the beginning.
The real wealth skill is knowing how to make a conscious call.
THE JOYDEEP QUESTION
You now know the number.
But do you understand the decision?
That’s where I want you to pause.
Because:
**A number can inform you.
Only awareness can help you decide.**
Welcome to Money Lab.